What Is a Good Credit Score? Credit Score Ranges Explained

Your credit score is one of those numbers that might not seem important until you actually need to use it.
Want to finance a car? Your credit matters. Buying a house? It matters. Applying for another credit card? Yep, it matters there too.
A good credit score doesn’t guarantee approval, but it can make things a lot easier. It can also help you qualify for better interest rates, which can save you a lot of money over time.
So, what exactly is considered a good credit score?
Let’s get into it.
What Is a Credit Score?
A credit score is a three-digit number lenders use to estimate how likely you are to repay borrowed money.
There are different credit scoring models, so you don’t have just one universal credit score. FICO is one of the most widely used scoring models, and its base scores range from 300 to 850.
The higher the number, the better you generally look to potential lenders.
Your FICO Score is calculated using information from your credit report and five main categories.
Payment History — 35%
This is the biggest factor.
Payment history looks at whether you’ve paid your credit accounts on time. Late payments, missed payments, and other negative information can hurt your score.
It’s pretty simple: pay your bills on time.
Amounts Owed — 30%
This category includes how much debt you owe and how much of your available revolving credit you’re using.
For example, if you have a credit card with a $5,000 limit and you’re carrying a $4,500 balance, you’re using a large percentage of the credit available to you.
Higher utilization can hurt your score.
Length of Credit History — 15%
The longer you’ve responsibly managed credit, the more information lenders have about your borrowing habits.
FICO considers things like the age of your oldest account, newest account, and average account age.
New Credit — 10%
Opening several new credit accounts within a short period can potentially hurt your score.
That doesn’t mean you should be scared to apply for credit. Just don’t go crazy applying for five or six cards at the same time because you saw some sign-up bonuses.
Credit Mix — 10%
FICO also looks at the different types of credit you’ve managed, such as credit cards, auto loans, mortgages, and installment loans.
You don’t need to run out and get one of each just to improve your score.
What Is Considered a Good Credit Score?
For base FICO Scores, 670 to 739 is considered good.
Here’s how FICO currently breaks down its ranges:
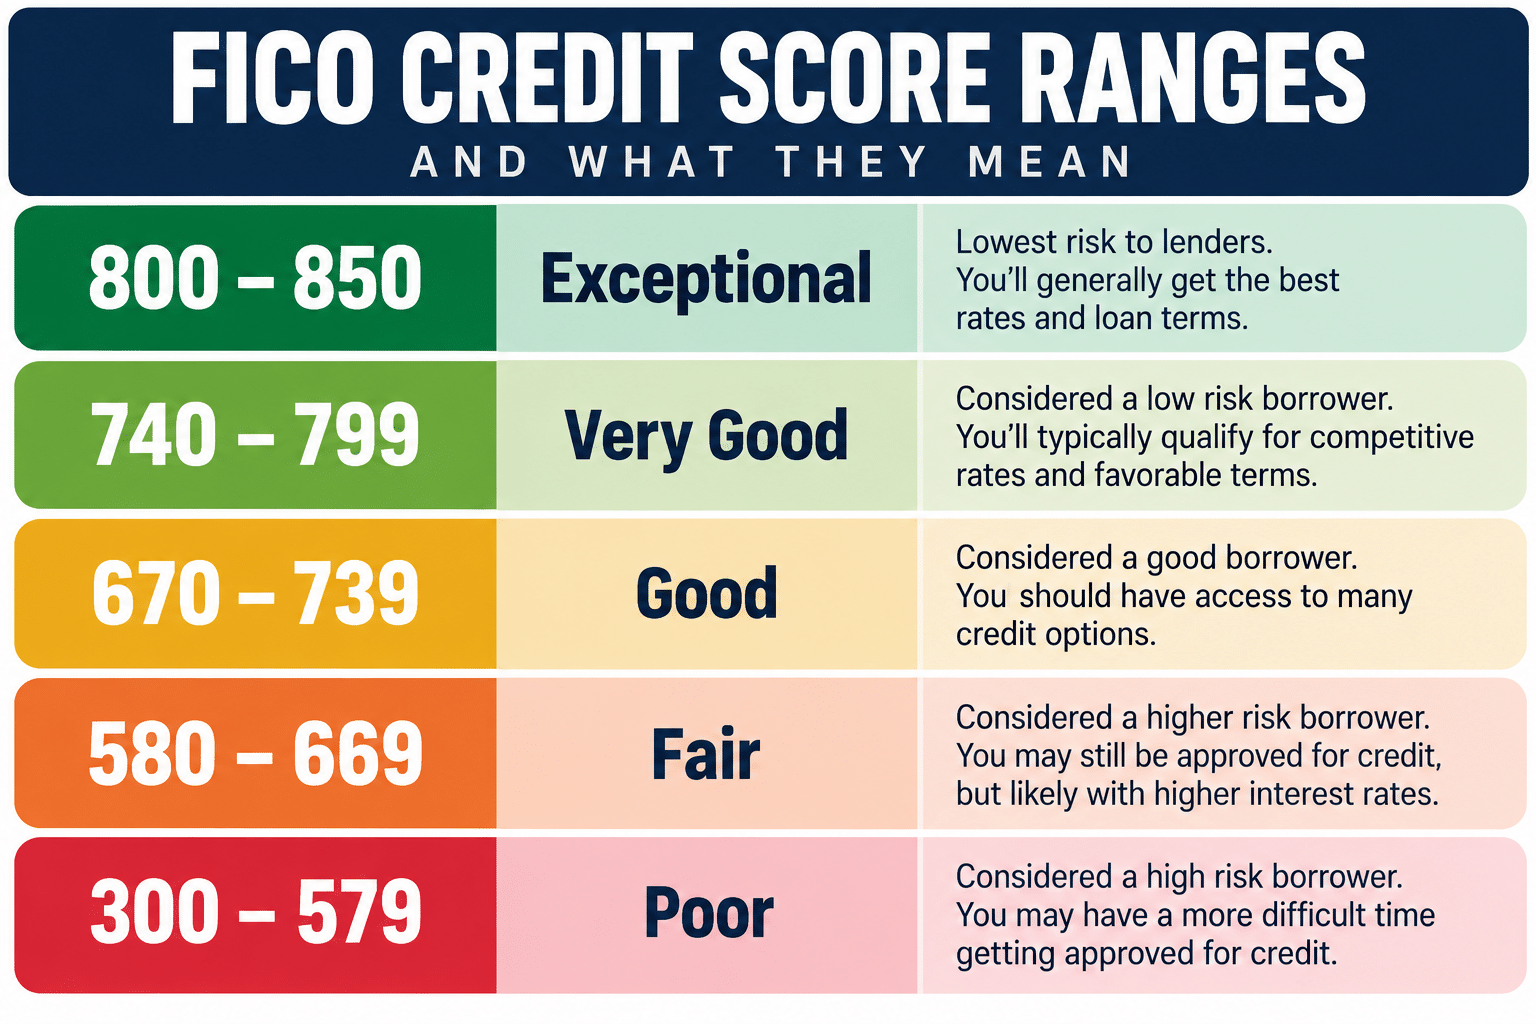
A 670 score doesn’t magically guarantee that every lender will approve you. Different lenders have different requirements, and they can look at other information besides your score.
Still, moving into the good, very good, or exceptional ranges can put you in a much better position when it’s time to borrow money.
Why Is a Good Credit Score Important?
The biggest reason I care about credit is simple:
I don’t want bad credit making things more expensive than they already are.
Here are several ways good credit can help you.
You May Have an Easier Time Getting Approved
Lenders use credit scores to help evaluate risk.
A higher score can improve your chances of getting approved for credit cards and loans, although lenders may also consider your income, existing debt, and other factors.
You Could Get Better Interest Rates
This is where having good credit can save you some real money.
Two people could borrow the same amount of money but end up paying significantly different amounts because one qualifies for a lower interest rate.
That difference becomes even more important when you’re talking about something expensive like a house or car.
Saving a couple of percentage points on a large loan isn’t pocket change.
Renting an Apartment May Be Easier
Landlords may review credit information when screening potential tenants.
A bad credit history doesn’t automatically mean you’ll be denied, but it can create another obstacle. Depending on the landlord, you might need a larger deposit, a cosigner, or additional documentation.
I’d rather have one less thing to worry about when applying for a place.
Your Credit History Can Matter for Some Jobs
There’s a lot of bad information online about employers checking people’s credit scores.
An employer may request certain credit or financial history as part of a background report where permitted, but they aren’t simply pulling the same credit score a lender sees. Employers using a background reporting company also generally need your written permission. State and local laws can place additional restrictions on these checks.
This is more common for certain jobs involving money or financial responsibilities.
How to Maintain a Good Credit Score

Getting your credit into a good range is one thing.
Keeping it there is another.
You don’t need to obsess over your score every day, but a few habits can help.
Pay Your Bills on Time
This is number one for a reason.
Payment history accounts for the largest portion of a FICO Score.
Set reminders or automatic payments if you have trouble remembering due dates. At minimum, make sure the required payment gets made on time.
Keep Credit Card Balances Under Control
You’ve probably heard that you should always keep credit utilization below 30%.
I wouldn’t treat 30% like some magical line where everything is perfect underneath it.
In general, using less of your available revolving credit is better than consistently being close to maxed out. FICO specifically notes that high utilization can indicate that someone is overextended.
If your balances are getting high, work on bringing them down.
Don’t Close Old Credit Cards Without a Reason
Older accounts can help your credit history, so don’t automatically close an old card just because you haven’t used it lately.
That doesn’t mean you should keep every card forever. An annual fee or other issue could make closing one reasonable.
Just understand how closing an account could affect your overall credit profile before doing it.
Check Your Credit Reports
Errors happen.
That’s why you should periodically check your credit reports and make sure the information is accurate.
You can currently request free weekly online credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com.
If you find incorrect information, dispute it with the appropriate credit bureau.
Don’t Apply for Credit Just Because You Can
Having good credit doesn’t mean you need another credit card every month.
Opening several accounts within a short period can work against you because new credit is part of the FICO scoring formula.
Be intentional.
You Don’t Need a Perfect Credit Score
I think this gets overlooked.
An 850 credit score sounds great, but you don’t need a perfect score to have good credit.
Once you’re in the higher ranges, you’re already in a much better position than someone dealing with poor credit.
The goal shouldn’t be to obsess over every tiny movement in your score.
The goal is to build a strong credit profile that helps you instead of costing you money.
What If Your Credit Score Isn’t Good Yet?
Work on the basics first.
Pay everything on time.
Get your credit card balances down.
Check your reports for errors.
Avoid constantly applying for new credit.
And give it some time.
I know improving credit can happen because I’ve done it myself. I was once in the low 500s and couldn’t even get approved for a $500 personal loan. I eventually increased my credit score by 168 points in nine months.
That didn’t happen because of some secret credit hack.
I started making better decisions and fixing the things that were hurting my credit.
If you’re currently trying to do the same thing, check out my guide on how to improve your credit score.
A good credit score isn’t about bragging that you have a 750 or 800.
It’s about options.
I want the option to qualify for a competitive rate if I need a loan. I want to be able to apply for an apartment or credit card without immediately wondering if my credit is going to screw me.
That’s why maintaining good credit matters.
You don’t have to be perfect. You just have to consistently do the things that move you in the right direction.
Pay on time. Keep your balances under control. Check your credit reports. Don’t apply for a bunch of unnecessary accounts.
Do that consistently, and you’ll put yourself in a much better position when you actually need your credit.
Like My Money Chronicles? Add us as a Preferred Source on Google to see more of our content in your search results.

Jason Butler is the founder of My Money Chronicles and an SEO consultant with over a decade of blogging experience. Since 2015, he has earned income through side hustles including blogging, eBay flipping, affiliate marketing, and freelance work while paying off over $64,000 in debt. His work has been featured in Forbes, Discover, Investopedia, and Yahoo Finance.