How to Budget Money: 9 Simple Steps That Actually Work

Budgeting doesn’t have to be complicated.
You don’t need a finance degree, an expensive app, or a complicated spreadsheet to figure out where your money goes. You just need a plan.
I’ve learned that having a budget isn’t about cutting out everything you enjoy. It’s about knowing what you can afford, staying on top of your bills, and making progress toward your financial goals.
Whether you’re trying to save more money, get out of debt, or stop wondering where your paycheck went, these nine steps can help you get started.
1. Set Financial Goals
Before creating a budget, figure out what you’re working toward.
Maybe you want to save $1,000, pay off a credit card, take a vacation, or eventually buy a house.
Whatever it is, give yourself a specific goal.
Instead of saying, “I want to save more money,” try something like, “I want to save $1,000 over the next six months.”
That means saving about $167 per month.
Some goals will take longer than others. Paying off a small credit card balance might take a few months, while saving for a house could take years.
The important thing is having something to work toward.
If homeownership is one of your goals, check out my guide on how to save money for a house.
2. Track Your Income and Expenses
You can’t create a realistic budget if you don’t know how much money you’re bringing in or spending.
Start with your monthly take-home income. Include your regular paycheck and any additional money from side hustles or other sources.
If your income changes from month to month, use a conservative estimate based on what you typically earn.
Next, look at your expenses.
Rent, utilities, groceries, insurance, subscriptions, transportation, eating out — write it all down.
And don’t forget those random purchases that seem small at the time.
Spending $12 here and $18 there might not seem like much, but it adds up.
You can use a budgeting app, spreadsheet, or regular notebook. Whatever helps you stay consistent is fine.
3. Categorize Your Spending
Once you know where your money is going, organize your expenses into categories.
I would start with three:
- Needs: Rent, groceries, utilities, insurance, and transportation.
- Wants: Entertainment, restaurants, subscriptions, and other nonessential purchases.
- Savings and debt payments: Emergency savings, investments, and extra debt payments.
Your essential expenses come first.
After that, figure out how much you can realistically put toward your other goals.
You don’t have to eliminate every fun purchase. The goal is to spend intentionally instead of letting your money disappear.
4. Try the 50/30/20 Budget Rule
The 50/30/20 rule is a popular way to divide your take-home income.
It suggests putting 50% toward needs, 30% toward wants, and 20% toward savings and debt payments beyond required minimums.
Here’s what that looks like if you bring home $3,000 per month.
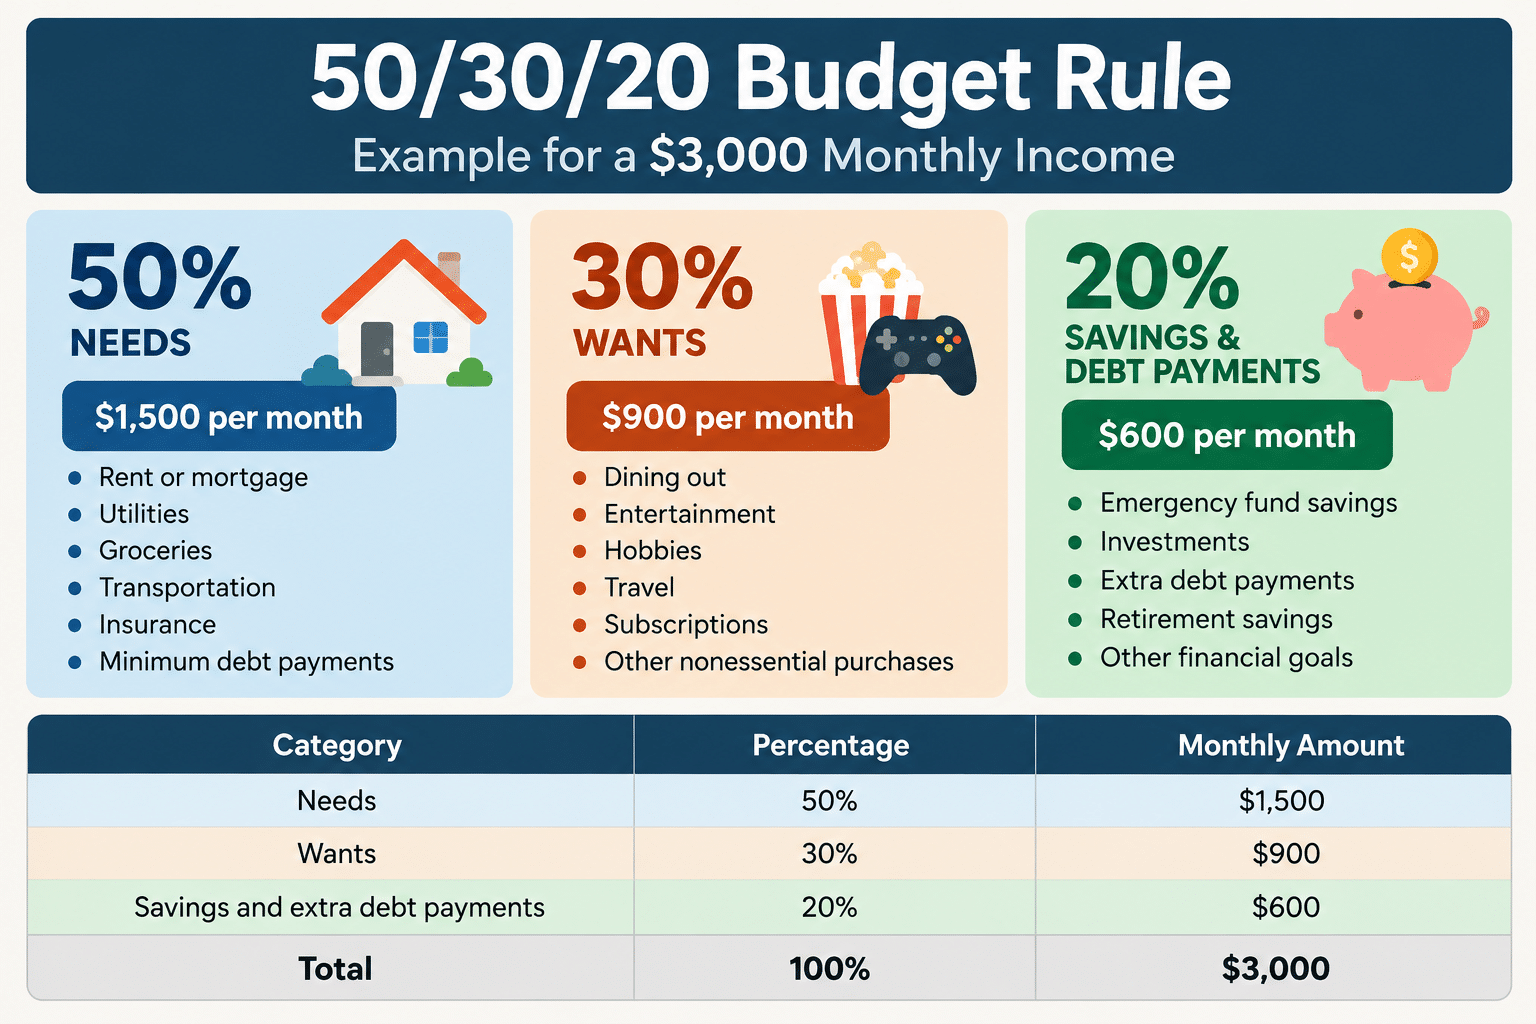
That’s a starting point, not a rule you have to follow perfectly.
If your rent, groceries, and other necessities already take up 60% of your income, you may need to adjust the percentages.
Don’t beat yourself up because your numbers don’t fit somebody else’s formula.
The best budget is one that works with your actual income and expenses.
The Consumer Financial Protection Bureau (CFPB) also provides budgeting resources to help you create a spending plan and manage your money.
5. Build an Emergency Fund
Life happens.
Your car might break down. You could lose your job. An unexpected medical bill might show up.
That’s why having an emergency fund matters.
Eventually, you may want enough saved to cover three to six months of essential living expenses. If your income is unpredictable, a larger cushion might make sense.
But don’t let that big number discourage you.
Start with $500 or $1,000 if that’s more realistic. You can build from there.
Consider keeping the money in a separate savings account, preferably one earning a competitive interest rate.
You want it accessible when something goes wrong, but not sitting in your everyday checking account tempting you to spend it.
For more ideas, read my guide on how to build an emergency fund.

6. Review Your Budget Regularly
A budget isn’t something you create once and never look at again.
Your expenses change. Your income might increase or decrease. New responsibilities come along.
I recommend checking your budget at least once a month.
See what worked and what didn’t.
Maybe you spent more on groceries than expected. Maybe your electric bill was higher. Or maybe you spent less on entertainment than you planned.
Make adjustments.
If your budget needs to change, change it.
There’s no reason to keep following numbers that no longer make sense.
7. Cut Unnecessary Spending
This doesn’t mean you have to stop enjoying life.
Start by looking for things you pay for but barely use.
That streaming service you haven’t watched in three months? Cancel it.
The gym membership you forgot about? Decide whether it’s worth keeping.
Then look at everyday spending.
Maybe you’re eating out four times a week when twice would work just fine. Maybe you’re making impulse purchases that you don’t even care about a week later.
You don’t have to cut everything.
Keep spending money on the things that matter to you. Cut back on the things that don’t.
If you’re looking for additional ideas, check out my article on ways to save money.
8. Make a Plan to Pay Off Debt
Debt can eat up a large part of your monthly budget, especially when you’re dealing with high-interest credit cards.
Two common repayment strategies are the debt snowball and debt avalanche.
With the debt snowball, you focus on paying off your smallest balance first while making minimum payments on everything else.
With the debt avalanche, you target the debt with the highest interest rate first.
The avalanche generally saves more money on interest, while the snowball can give you quicker wins that help you stay motivated.
I’ve dealt with significant debt myself, so I know that paying it down isn’t always easy.
Pick a method you can stick with.
You can also consider debt consolidation if it genuinely lowers your borrowing costs. Just make sure you understand the interest rate, fees, and repayment terms before signing anything.

9. Automate Your Savings and Bills
One of the easiest ways to stay consistent is to automate what you can.
If you want to save $100 every month, schedule an automatic transfer into your savings account.
That way, you don’t have to remember to move the money.
You can also automate bill payments to help avoid missed due dates and late fees.
Just make sure there’s enough money in your checking account before those payments go through. Otherwise, you could end up with overdraft fees or returned payments.
If your income varies, automatic reminders might work better than scheduling every payment.
What If Your Budget Isn’t Working?
First, figure out why.
Are you consistently spending more than planned? Did you underestimate your bills? Is your income simply not enough to cover your expenses?
Sometimes the problem isn’t that you’re buying too much coffee. Sometimes you genuinely need more income. If you’ve already cut what you reasonably can, look for opportunities to bring in additional money. That could mean overtime, freelance work, selling things you don’t use, or starting a side hustle.
I’ve used side hustles for years to bring in extra money, and they can make a difference when your regular income isn’t enough.
Check out my 100 side hustle ideas if you need somewhere to start.
Learning how to budget money isn’t about being perfect.
You’re going to have months where unexpected expenses come up or you spend more than planned. That doesn’t mean your budget failed.
Make the necessary adjustments and keep going. Start with your income, figure out your expenses, set a few goals, and build a plan that makes sense for your life. You don’t have to figure everything out overnight.
The important thing is getting started and being consistent.
Like My Money Chronicles? Add us as a Preferred Source on Google to see more of our content in your search results.

Jason Butler is the founder of My Money Chronicles and an SEO consultant with over a decade of blogging experience. Since 2015, he has earned income through side hustles including blogging, eBay flipping, affiliate marketing, and freelance work while paying off over $64,000 in debt. His work has been featured in Forbes, Discover, Investopedia, and Yahoo Finance.